THE SHORT ANSWER
Insurance for a salvage title car is not guaranteed. Until repairs and a state inspection are done, the car generally cannot be driven legally, so a standard road policy has little to attach to. Once it carries a rebuilt brand, some insurers will quote it and some decline. Confirm the brand with a VIN title check, then get a written answer from an agent before you hand over money.
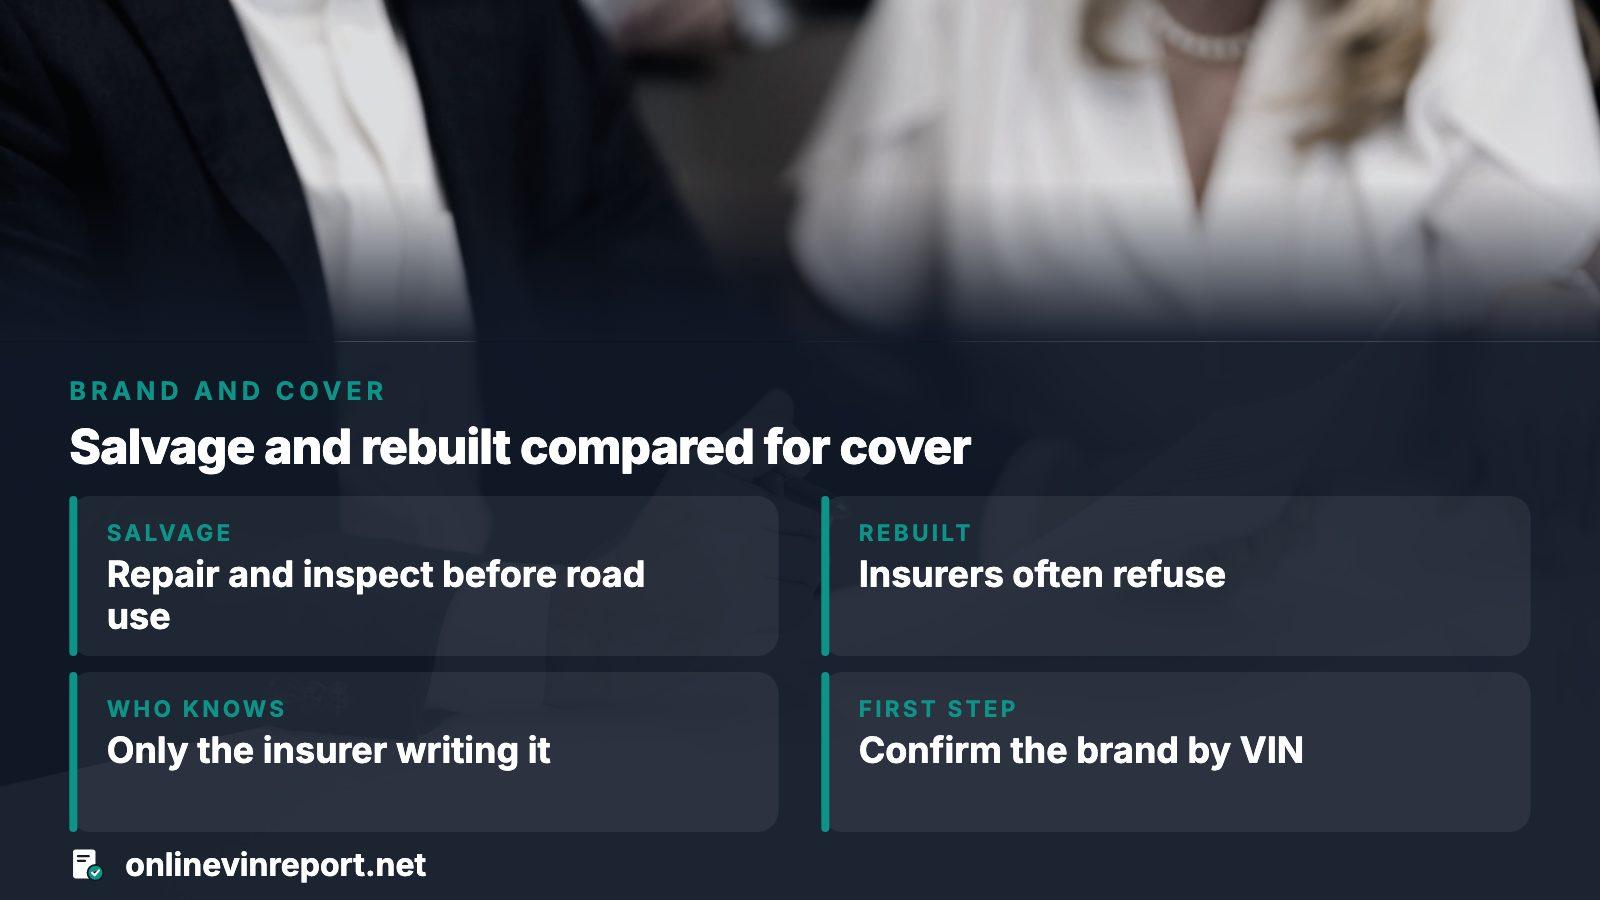
- Salvage brand
- Car must be repaired and inspected before road use
- Rebuilt brand
- Texas DMV says insurers often refuse these
- Who knows
- Only the insurer that would write your policy
- First step
- Confirm the real brand by VIN
Why the title brand decides your insurance options
An insurer prices risk on a car it can see clearly. A salvage brand says another insurer, or the state, already decided the repair bill outran the car's worth. That single fact makes underwriters cautious, because the paper says nothing about which panel, frame member or airbag was involved.
The brand also controls what the car may do. Under Texas DMV's wording, a branded salvage car is off the road until someone repairs it and it passes inspection. Before then, the state will only issue paperwork that keeps it off the road, or let the owner scrap it. A policy for a car that cannot legally be driven is a different product from a normal one, and many carriers simply do not sell it.
Salvage and rebuilt are two different insurance questions
People ask about both as if they were one problem. They are not. A car with a live salvage brand is a project, and the practical question is whether you can park, store or tow it under any cover. A car with a rebuilt brand has passed an inspection and can be registered, so the question becomes which insurers will write it and on what terms.
| Brand on the title | What the car can do | Insurance question to ask |
|---|---|---|
| Salvage | Cannot go back on the road until rebuilt and inspected | Is any cover offered while it is parked or being repaired? |
| Rebuilt | Can be registered after inspection | Will you quote liability, and also collision and theft or storm cover? |
| Owner retained | Insurer paid a total loss and the owner kept the car | Is the earlier claim visible to you, and does it change the offer? |
Definitions of rebuilt shift a little from state to state, so use the state where the car will be registered as your reference.
What the official pages actually say, and what they leave out
On its rebuilt page Texas DMV tells shoppers that insurers frequently say no, and to speak with an agent first. Its salvage page adds that buyers should think about whether the car can be insured at all, next to what it could resell for.
What I could not find on any official page I opened was a rule telling insurers which coverages they must offer on a branded car. No agency page promised that a quote exists. Treat any website that says a salvage car is always insurable, or never insurable, as guessing. The answer sits with the specific insurer, the specific car and the specific state.
Why the gap matters
A DMV can tell you how to retitle a car. It cannot tell you whether a carrier will write a policy on it. Those are separate decisions made by separate parties.
Questions to put to an insurer before you pay the seller
Do this with the VIN in hand and the brand confirmed, not from a seller's description. Agents can only answer for the car in front of them.
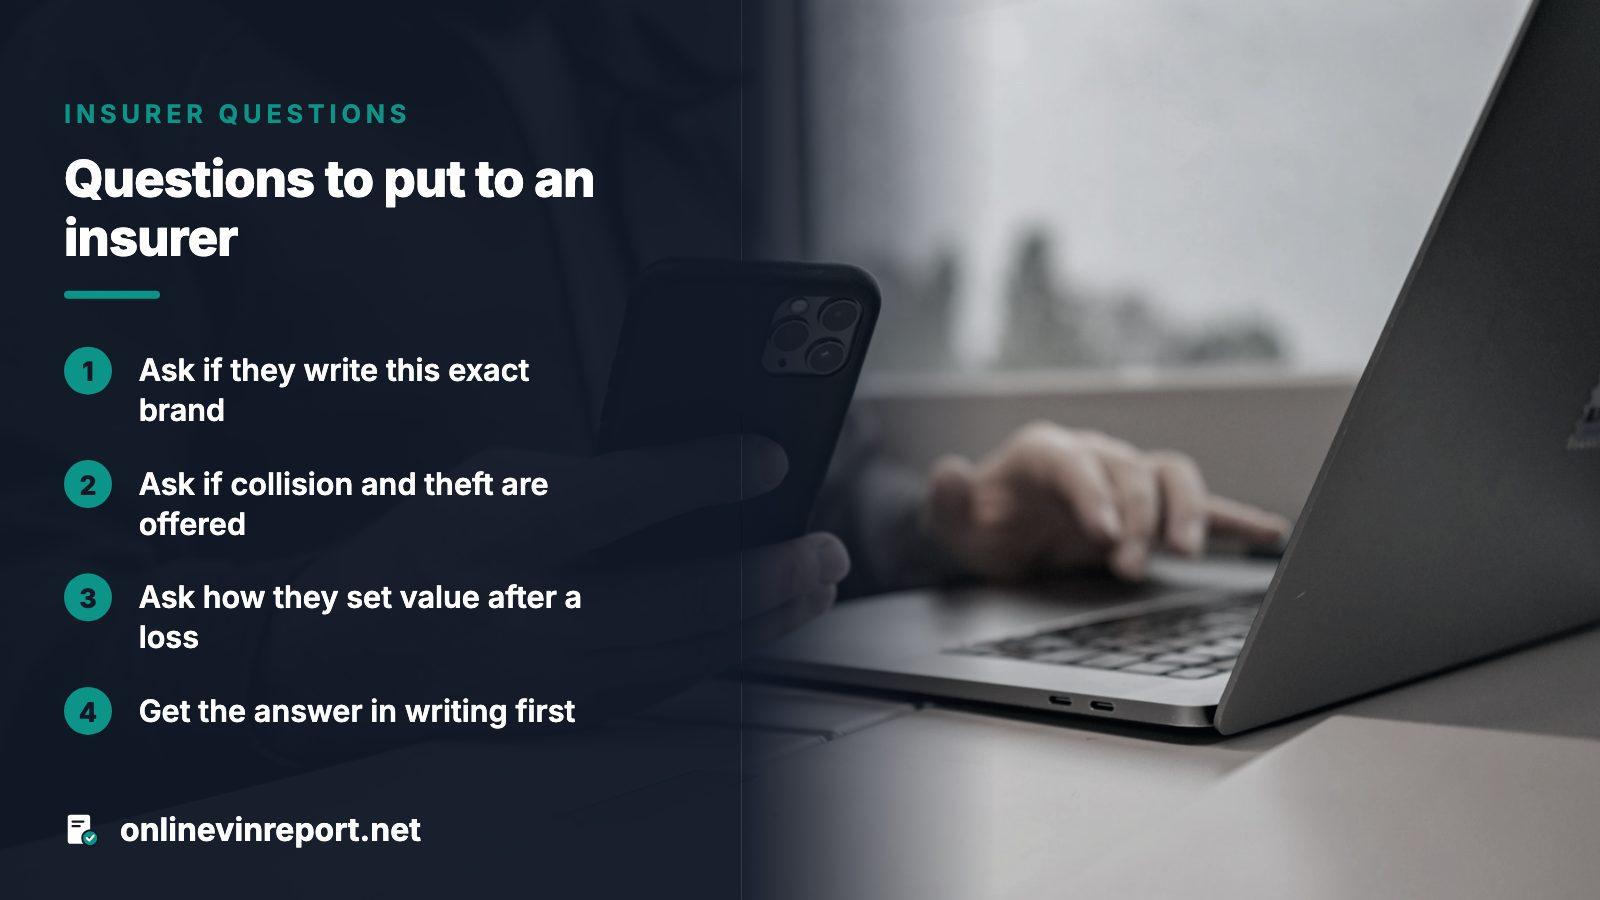
- Do you write a policy on a car with this exact brand in this state?
- Is liability the only option, or are collision and theft or storm cover available too?
- How would you set the car's value after a loss, given the brand?
- Will you want photos of the repairs, a receipt trail or an inspection record first?
- Can you give me the answer in writing before I buy?
Getting two or three answers beats one. If every carrier you try declines, you have learned something useful for free, and so has your wallet.
Value is the quiet catch even when cover is offered
Texas DMV adds that a rebuilt car will always be worth far below a similar car that was never written off. That matters at claim time. If a policy pays out on the market value of a branded car, a total loss on a rebuilt car pays less than the same loss on a clean one, and what you paid the seller is irrelevant to that figure.
So a cheap price can hide a thin safety net. If you borrow to buy the car, the lender may also care about the brand and about what the insurer will cover. Settle those questions before the deal, not after a crash.
What the damage history does to the repair itself
Texas DMV suggests a buyer of a rebuilt car find out how extensive the damage was, who repaired it, whether the frame was aligned and whether an independent mechanic signed off. It also flags that a replacement part is sometimes improvised by welding salvaged sections.
An insurer may ask the same things, because the answers decide how likely the car is to be involved in a bigger loss later. Photos and invoices from the repair help both you and the agent. Without them, expect a more careful and possibly more expensive answer.
If you already own the car
Hold off ending your policy when an insurer declares a total loss. Nevada DMV's order of steps is plates off, registration cancelled or plates surrendered, and only then the policy ended, since a live plate without cover can bring a fine from $250.
If the insurer totaled it, who handles the paperwork
When you keep a car after a total-loss settlement, the title steps differ by state. In California, an insurer that pays a settlement must obtain the salvage certificate within 10 days, and an owner with no settlement does it personally. Nevada gives an owner 30 days when no insurer is taking the car.
Texas uses brand names such as Owner Retained and Salvage Retention when the owner keeps a car. Either label on a VIN report points to an earlier insurer loss. That earlier claim is the reason the next insurer will look harder.
Run the VIN title check before you call anyone
A seller may say the car is fine, clean or just cosmetic. The title brand is a record, not an opinion, and it decides everything above. Federal NMVTIS data pulls from state titling agencies, recyclers, salvage yards and insurance carriers, which is why a VIN check can show a brand the seller never mentioned.
The free NICB VINCheck is a sensible first screen. It covers cars reported by participating insurers, allows five searches per 24 hours from one IP address, and is not a full history. A fuller VIN title report on this site starts with a free preview of the brands, then costs a single payment, with prices on the pricing page. Use the brand it finds as the exact wording you give each insurer.
Where this information comes from
- Texas DMV: rebuilt vehicles — insurance warning, value drop and repair questions for rebuilt cars
- Texas DMV: salvage vehicles — road-use rule, brand meanings and buyer tips
- Nevada DMV: salvage vehicles — who applies for the title and the order for cancelling insurance
- California DMV: total loss salvage — insurer duty after a settlement
- NMVTIS FAQ — insurer reporting of salvage and total-loss cars
Sources and photos: Facts checked against the sources above in November 2026. Photos by Everett Pachmann, Anastasiia Nelen and Carrie Allen www.carrieallen.com on Unsplash; diagrams by OnlineVINReport.
Keep reading
- Salvage title VIN check: run it online before you payRun the brand check before calling an insurer.
- What is a rebuilt title? What it means and what a VIN title check showsSee how the rebuilt brand differs from salvage.
- Rebuilt title inspection: what the state checks and what a VIN title check addsLearn what inspection moves a car toward road use.
- Why a salvage title is bad, and how a VIN check shows it firstWeigh the other downsides of a written-off car.
Frequently asked questions
Can I get full coverage on a rebuilt title car?
Some insurers offer it and some will only write liability or decline outright. No official page I read sets a rule either way. Ask each carrier about your exact VIN and state, and request the answer in writing so the quote still stands on the day you buy.
Can I insure a car that still has a salvage title?
A salvage car generally has to be rebuilt and inspected before road use, so ordinary road cover is hard to arrange. Some carriers may discuss cover for a parked or in-repair car. Ask directly, and do not assume the seller's insurance history applies to you.
Why do insurers hesitate over branded cars?
The brand shows a previous total-loss call and says nothing about how the repair was done. That uncertainty makes the car harder to price. Repair photos, receipts and an independent inspection report give an underwriter something concrete to work from.
Does a VIN check tell me if the car can be insured?
No. It shows the brand and related records, which is the information an insurer will ask about. Whether a carrier writes the policy is its own decision, so use the report to give each agent accurate details.
Should I cancel insurance after my car is totaled?
Not first. Nevada DMV advises dealing with plates and registration before ending the policy, since a registered car with no cover can bring a fine. Check your own state's order of steps with its DMV before you cancel.
Now check the car itself
The guide explains what to look for. The report shows what this VIN has on record.